FINANCE PRODUCTS
Refinance
Releasing capital from equipment you already own, and putting it back to work.
What it is
Raising money against an asset the business already owns. The funder advances a sum based on the asset's value, takes security over it, and you repay across an agreed term.
It's sometimes called capital release, or sale and leaseback depending on how it's structured. The principle is the same. Value that's currently sitting still inside a machine or a vehicle becomes cash the business can use.
The asset carries on working throughout. It stays where it's and you keep using it exactly as before.
What people use it for
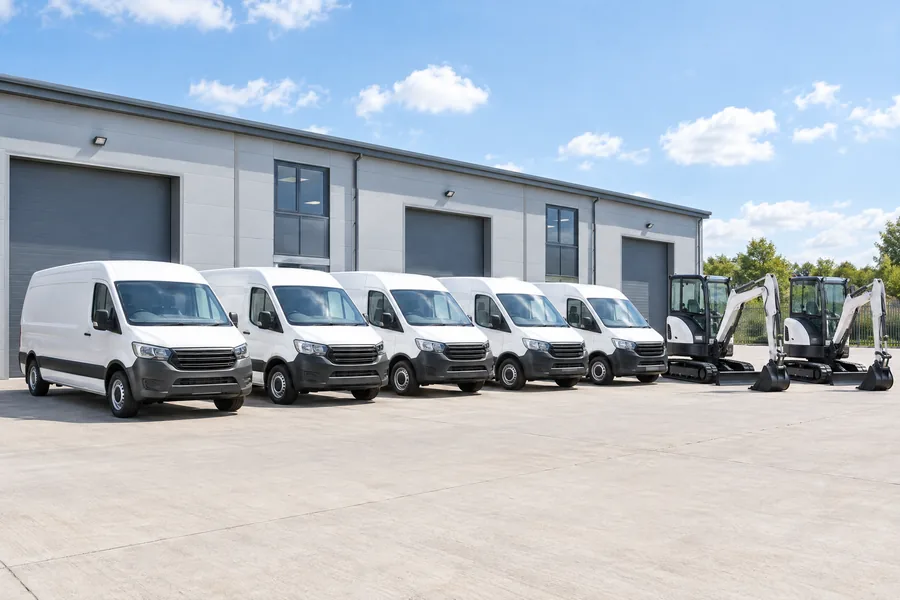
A haulier with a paid-off fleet and a chance to take on a contract that needs working capital before it starts paying. A contractor whose yard is full of owned plant but whose balance won't cover the next payroll run. A manufacturer who bought a machine outright two years ago and now wishes some of that cash was still available.
It also comes up when a business wants to tidy up its commitments. Several agreements ending at different times on different terms, replaced with one arrangement that's easier to manage and easier to forecast against.
The common situation is a business that's asset rich and cash tight, which is far more usual than it sounds, particularly in construction, haulage and manufacturing.
What can be refinanced
Assets the business owns outright, or close to it. The funder is lending against the value that's genuinely yours.
- Commercial vehicles, tractor units and trailers
- Excavators, telehandlers, dumpers and site plant
- Production machinery and CNC equipment
- Agricultural machinery
- Specialist and high value equipment
Age matters, but less than people expect. What matters more is whether there's a resale market for the asset, because that's what underpins the funder's position. A well maintained machine with a strong second-hand market can often be refinanced years into its working life.
How it works
The funder needs to establish two things: what the asset is worth, and that you own it.
Valuation is based on asset type, age, hours or mileage and condition. Some funders accept a desktop valuation on common equipment. Others want an inspection, particularly for specialist kit or higher values.
Proof of ownership means the original invoice, plus evidence that any previous finance has been settled. This is the step that most often slows things down, so it's worth locating the paperwork before you start rather than halfway through.
Once agreed, the funder advances the sum and takes security over the asset. You continue using it as normal. The agreement runs for a fixed term with fixed repayments, and at the end the security is released.
If the asset still has finance outstanding, refinancing is sometimes still possible. The existing agreement is settled as part of the arrangement and what you release is the balance above it.
Ready to talk it through?
Tell us what you're trying to do and we'll come straight back to you.
Enquire nowTHE HONEST BIT
Three things worth knowing before you commit
The asset becomes security
This is the part that matters most. Something you currently own outright will have a funder's interest over it, and if the repayments stop, that asset is at risk. It's a straightforward trade and often the right one, but it should be a decision rather than a surprise.
You won't release the full value
Funders advance a proportion of what the asset is worth, not all of it, because their position depends on being able to recover if things go wrong. Going in expecting full market value usually leads to disappointment.
Refinancing to cover a loss is a warning sign
Releasing capital to fund growth or a specific opportunity makes sense. Releasing it to cover ongoing losses turns an owned asset into a monthly commitment without solving anything. We'll say so if that's what it looks like.
Questions we get asked
Can I refinance an asset that still has finance on it?
Often yes. The existing agreement is settled as part of the new arrangement and what you release is the balance above it. How much that comes to depends on how far through the original term you're and what the asset is now worth.
How is the asset valued?
On type, age, hours or mileage and condition, measured against what similar assets are selling for. Some funders accept a desktop valuation for common equipment. Two funders can reach different figures on the same machine, which is one reason it's worth looking at more than one.
Do I keep using the equipment?
Yes. It stays where it's and carries on working throughout the agreement. The funder takes security over the asset rather than possession of it, so nothing about how you use it changes. You simply have a monthly commitment against something that previously had none.
What paperwork do I need?
The original purchase invoice, and evidence that any earlier finance has been cleared. Recent maintenance records help for older assets. This is the part that most often causes delay, so it's worth digging it out before you start.
Is there a minimum value?
Most funders have one and it varies. Below a certain point the cost of valuing and documenting the asset outweighs the benefit for everyone involved. Tell us what the asset is and we'll tell you quickly whether it's worth pursuing.
Next step
Tell us what you own, roughly what it's worth and what you want the capital for. We'll tell you whether refinance is the right route or whether something else fits better.
RELATED
Vehicle & asset finance, if you're buying rather than releasing. Personal guarantee insurance, if a funder asks you to sign one.
Worth reading: what an asset finance broker actually does that a bank can't.